Tata Capital > Blog > Credit Score > What is a tradeline on a credit report, and how does it work?

 30 October 2026
 10 mins read
 1693


Your credit report can have a tradeline, meaning an individual credit account listing. Some examples of tradelines include credit cards, car loans, student loans, and mortgages. It can be an active or a closed line of credit reported to major credit bureaus. The purpose of a tradeline is to provide a detailed record of your borrowing and repayment history. Lenders use the information to assess your creditworthiness and estimate your credit score. You can review and understand your credit tradelines yourself through the official credit bureaus to determine whether there is a need for improvement.
The term trade credit, meaning an individual account listed on your credit report, is commonly used in the credit industry.
Your credit report tells lenders about your credit status and creditworthiness when you apply for a credit card, loan, or mortgage. It consists of various metrics and records that summarize your current situation.
The tradeline is a key metric that determines if you qualify for credit or not by tracking all your credit activity and displaying it on your credit report. Frequently reviewing your tradeline can help you manage your credit effectively and improve your chances of securing credit.
This article explores what a tradeline on a credit report is in detail and explains everything you need to know about it.
A tradeline is a record of credit transactions that shows up on an individual’s credit report. It is created after someone is granted permission to open a credit account. Every tradeline contains information on the type of account, the lender, the credit limit, and the payment history.
For example, if someone has four credit accounts, their report will show four tradelines, each reflecting specific details about those accounts. Tradelines are essential for calculating an individual’s credit score.
A tradeline is part of your credit profile, which offers a summary of your credit history. Every tradeline is equivalent to a single credit account and contains components that enable creditors to determine your creditworthiness. Here are the primary components of a tradeline on your credit report:
Tradelines on your credit report are classified into three main types:
Revolving accounts are a common type of tradeline. They let you borrow money, up to a predetermined amount, and pay it back gradually. Credit cards are the most common type of revolving account. Your spending patterns may cause changes to your available credit, payments, and balances. Credit utilization, which is determined by comparing your current balance to your credit limit, is a crucial component of revolving accounts. Your credit score is greatly impacted by this calculation.
Installment loans allow you to take out a fixed loan amount and pay it back over a predetermined length of time in fixed installments. Installment loans, when combined with revolving accounts to form a varied credit mix, have the potential to improve your credit score.
Some tradelines may not fit into the previous categories. For example, landlords have the ability to disclose rental information, and utility payments made through third-party providers may show up. Your credit history and payment history are largely impacted by these accounts, not the overall amount owing.
Let’s understand the tradeline’s meaning with a simple example.
Suppose you have a credit card with a limit of Rs. 1 lakh. The tradeline on your credit report may show the lender’s name, account type, opening date, credit limit of Rs. 1 lakh, current balance, payment history, and account status. If you regularly pay your bills on time and keep your balance low, the tradeline will reflect your positive credit behavior.
When you apply for a loan or credit card, the lender will review these details to understand how responsibly you manage credit and, accordingly, determine your eligibility.
You can verify the accuracy and timeliness of the information reported by reviewing your tradelines. Your credit score could be impacted if the tradeline information is incorrect.
By monitoring your tradelines, you can identify any illegal activity or fake accounts created in your name.
You can improve your creditworthiness by taking corrective action to address unfavorable tradelines, such as inaccurate or late payments.
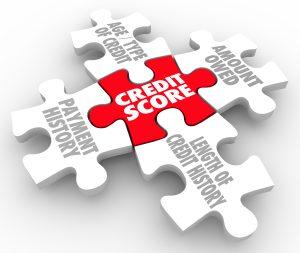
Tradelines play a vital role in shaping your credit score by influencing key factors that determine your credit health. Here’s how they impact your score:
Once a tradeline’s meaning is clear to you, it is vital to understand whether it hurts your credit score. If a tradeline shows negative information, it can certainly hurt your credit score. Events like late payments, missed Equated Monthly Installments (EMIs), loan defaults, high credit card balances, or settled accounts can all lower your score. Your credit profile can get hurt by even a single missed payment.
The negative entries on your credit report can remain on it for several years. However, your score can improve over time if you make timely payments and manage credit responsibly.
Also Read – Loan for low credit score
When you are removed from a tradeline, the account stops appearing on your credit report. This can affect your credit score in different ways:
If the tradeline had a long record of on-time payments, removing it could reduce the amount of positive information on your credit report. This may have a negative impact on your credit score.
If the tradeline were a credit card account, its removal could lower your total available credit. As a result, your credit utilization ratio may rise, which can hurt your credit score.
Older accounts help demonstrate a long credit history. If you are removed from an older tradeline, the average age of your accounts may become lower, which can affect your credit profile.
Closing or paying off a tradeline affects your credit score in different ways. If you pay off a loan, your debt burden decreases, which may help your credit profile. However, if you close a credit card, there can be a drop in your total available credit. It can increase your credit utilization ratio and eventually lower your score. If there are closed accounts with a good payment history, it may continue to benefit your credit report for some time.
The overall impact depends on your credit history, account age, and how you manage your remaining credit accounts.
To view the tradelines on your credit report, follow these steps:
You can use a paid credit monitoring service that offers frequent updates on your credit status, or you can ask the major credit agencies for a free credit report.
Once you have your credit report, locate the “Credit Accounts” or “Tradelines” section. All of the accounts that have been reported to the credit institutions are included in this section.
Examine each tradeline for accuracy. Verify that all the information is accurate, including the account status, payment history, and outstanding balances. Make sure to dispute any disparities with the right credit institution.
The steps you need to follow to get a tradeline added to your credit report are as follows:
Generally, you cannot add a tradeline manually. It needs to come from a legitimate credit account reported by a lender.
Tradelines can stay on your credit report for several years. It depends on the account status. If there are open and active accounts, they usually stay on your report as long as they remain active. Closed accounts in good standing may continue to appear for many years and can help show your credit history. Negative tradelines, such as accounts with late payments or defaults, may also remain on your report for several years. The exact duration varies based on credit bureau policies and the type of information being reported.
Understanding the many types of tradeline credit is essential for maintaining a high credit score. By routinely evaluating your tradelines, you can confirm their accuracy, identify potential fraud, and take steps to improve your creditworthiness. In the end, having knowledge about your trade line credit entries helps you make more informed decisions and gradually improve your credit score.
For more insights and expert guidance on managing your trade line credit scores, visit the Tata Capital website or download the app today.
There is no fixed number of tradelines that can help you build a good credit score. If you have a mix of 2 to 4 well-managed tradelines, such as credit cards and loans, it can help you build a strong credit history.
Yes. If you find an incorrect tradeline on your credit report, you can raise a dispute with the credit bureau and provide supporting documents.
A tradeline is a credit account on your report. On the other hand, a credit inquiry is a record showing that a lender checked your credit report.
Yes, being added as an authorized user on someone else’s tradeline can improve your score if the account has a positive payment history. However, the impact depends on the lender, credit bureau, and account details.
A negative tradeline can affect your CIBIL score for several years. However, its impact usually decreases as the account becomes older.
A primary tradeline belongs to the account holder responsible for payments. On the other hand, an authorized user tradeline belongs to someone added to the account by the owner.
Yes, a paid-off loan with a good repayment history can remain on your credit report and continue supporting your credit profile.
If the same account appears as two different tradelines on your credit report, it can be due to reporting errors, account transfers, or updates from lenders. You must review the details and raise disputes against errors if required.


 Previous Post