Tata Capital > Blog > Credit Score > Maximum Credit Card Limit in India: How to Get a High Limit?

 28 October 2026
 7 mins read
 3080

Are you looking to buy a credit card or want to know how to make the most of your existing one? Here, understanding the maximum limit of a credit card in India is crucial to ensure seamless financial planning and budgeting.
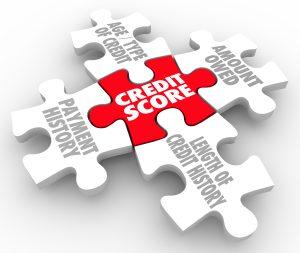
The maximum credit card limit in India depends on various factors like credit score, income, and credit history. Typically, an individual’s credit limit should not be more than twice their monthly income.
However, it can also depend on the issuing authority that sets the limit based on other eligibility factors. In this article, we’ll explore what is the maximum credit limit on a credit card in India and the factors that influence it.
A credit limit is the maximum amount a holder can spend using their credit card. While the Reserve Bank of India (RBI) has not standardised a maximum credit limit on credit cards in India, many financial institutions set limits based on an individual’s credit profile. A significant factor determining your credit limit is your financial reliability, which is determined by your monthly income and creditworthiness.
Therefore, two individuals holding the same credit card type may have different credit limits. An individual with a good financial profile will enjoy a higher credit score and credit limit. The issuing entity rests its confidence in your credit score, which indicates the ability to repay the credit borrowed.
The maximum credit card limit in India depends on the lending institution’s policies and your creditworthiness.
The following are the various factors that influence your credit card maximum limit –
There is more than one type of limit available on credit cards. These limits are set by the institutions issuing your credit card.
Apart from understanding how your credit limit is determined, there are a few ways to make the best use of your credit card-
Timely payments and responsible use of credit can increase your credit limit over time. Here are some ways to manage and increase your maximum credit limit on a credit card in India –
Your credit limit plays an important role in deciding your loan eligibility. A higher credit limit gives you more spending room, but what matters is how much of that limit you actually use. When you use only a small part of your total credit limit, your credit utilisation stays low. This shows lenders that you manage credit responsibly and do not depend heavily on borrowed money.
Low credit utilisation also helps maintain a strong credit score, which is one of the first things lenders check before approving a loan. A good score improves your chances of loan approval and may also help you get lower interest rates and better repayment terms.
There are many misunderstandings about having a high credit limit credit card. Let’s clear some common myths:
Myth 1: Higher Credit Limit Encourages Overspending
A high credit limit credit card does not force you to spend more. It depends on your spending habits. If you are disciplined, a higher limit simply gives you flexibility and support during emergencies or large expenses.
Myth 2: High Credit Limit Credit Cards Can Harm Your Credit Score
This is not true. A high credit limit credit card can improve your credit score if you use only a small portion of it. Low credit usage shows good credit control and lowers risk in the eyes of lenders.
Myth 3: Paying the Minimum Amount is Enough
Paying only the minimum increases long-term debt. Always try to pay more to reduce interest and clear balances faster.
Myth 4: You Should Always Use Your Full Limit
Using too much of your limit can hurt your score. It’s better to keep usage below 30% of the credit card’s maximum limit.
Your credit card maximum limit is a reflection of your creditworthiness. Timely payments, spending habits, and income play a huge part in determining your credit score and maximum credit limit on a credit card in India. If you are considering applying for a new credit card or increasing the limit on your existing card, check your credit score first.To learn more, visit the Tata Capital website or download the app today!
The highest credit card limit can range from lakhs to a few crores.
The maximum credit limit is the maximum amount a credit issuing authority can extend to its client. It can vary depending on the lender’s policies and your credit profile.
The highest credit card limit in India can range from lakhs to a few crores.
The credit card maximum limit is the maximum amount a credit-issuing authority can extend to its client. The highest limit credit card in India can vary depending on the lender’s policies and your credit profile.
There is no fixed highest credit card limit in India for salaried professionals. Banks decide limits based on income, job stability, credit score, repayment history, and existing debts, which can range from a few lakhs to higher amounts.
Premium credit cards usually offer the highest limits in India. These are given to high-income individuals with strong credit profiles. The exact limit varies by bank, income level, and past credit behaviour.
You can increase your credit card maximum limit by paying bills on time, keeping low card usage, improving your income, updating income documents, and requesting a limit increase through your bank’s app or customer service.
Having a high credit limit does not harm your CIBIL score. In fact, it can help improve your score if you use only a small portion of the limit and make timely payments consistently.
Banks usually ask for recent salary slips, bank statements, income tax returns, or proof of increased income to decide the maximum limit of a credit card. Self-employed individuals may need business income documents and updated financial statements.
No, RBI does not set a fixed cap on the maximum limit of credit card. Banks are free to decide limits based on their internal policies, risk checks, customer income, and overall creditworthiness.
The total credit limit is the maximum limit of credit card that the bank allows you to spend. The available credit limit is the remaining amount after subtracting your current spending and pending dues from the total limit.


 Previous Post