Get the Tata Capital App to apply for Loans & manage your account. Download Now

Blogs

SUPPORT

Tata Capital > Blog > Credit Score > Equifax Credit Score: What It Means and How to Check Yours for Free

Credit Score

Equifax Credit Score: What It Means and How to Check Yours for Free

Equifax Credit Score: What It Means and How to Check Yours for Free

Apply for a loan or credit card in India and there is a good chance the lender pulls your Equifax credit score as part of the decision, not just the CIBIL score most people have heard of. Equifax is one of four credit bureaus licensed by the RBI to track how Indians borrow and repay, and its score can genuinely differ from what another bureau reports on the same person.

This guide explains what is Equifax credit score, how it is calculated, what the numbers actually mean, and how to check it online for free in a few minutes.

What is Equifax Credit Score?

An Equifax credit score is a three digit number, generated by Equifax Credit Information Services, that sums up how reliably you have handled credit in the past, including loans repaid on time, credit cards managed well, or defaults if any.

Lenders pull this number (and the fuller credit report behind it) before approving a loan or card, using it as a quick, standardised read on risk.

Equifax is one of four RBI licensed credit bureaus in India, alongside CIBIL, Experian and CRIF High Mark. Banks and NBFCs are free to check any one of them, or more than one, before lending.

Key Highlights of Equifax Credit Score

  • One of four RBI licensed bureaus in India, alongside CIBIL, Experian and CRIF High Mark
  • Credit score can be checked online for free, with no impact on the score itself
  • Credit score ranges from 300 to 900, with a higher number signalling lower credit risk, and a lower number signalling higher credit risk
  • Score is calculated on the basis of your repayment history, credit utilisation, credit mix and recent loan enquiries
  • Scores may differ from CIBIL or Experian due to the proprietary calculation models of Equifax

 Equifax Credit Score Meaning: How It Is Calculated

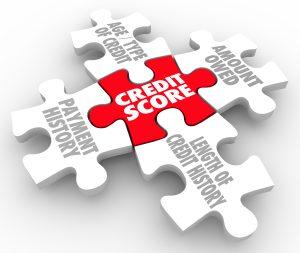
The Equifax credit score meaning comes down to how it’s built. The bureau collects your repayment data from banks and NBFCs and runs it through its own scoring model. A few factors carry the most weight.

Payment history matters most, every EMI and credit card bill paid on time (or missed) gets recorded and shapes the score for years afterward.

Credit utilisation, how much of your available credit limit you’re actually using, is next. Staying under roughly 30% of credit utilisation tends to help.

The mix of credit you hold (a blend of secured loans like a home loan and unsecured ones like a credit card, versus only one type) factors in too, along with how many new credit applications you have made recently, since a flurry of enquiries in a short window can read as financial stress to a lender.

Equifax Credit Score Range and What It Means

The Equifax credit score range runs from 300 at the low end to 900 at the top, and where you land within that band tells a lender roughly how risky you look on paper:

Score RangeCategoryWhat It Signals
800-900ExcellentLowest-risk borrower, easiest approvals and the most competitive rates
740-799Very GoodStrong repayment history, high approval odds on most products
670-739GoodAcceptable risk, usually qualifies for competitive interest rates
580-669FairSome lenders approve, but often with higher rates or stricter terms
300-579PoorHigh risk, approvals are difficult and may need additional security

What is the Highest Equifax Credit Score?

The Equifax highest credit score achievable is 900, though in practice very few people sit right at the ceiling. Anything from 800 upward puts you in the “Excellent” band, which is where lenders extend their best interest rates and the fastest approvals, since there is little in your history to flag as risk.

Why Your Equifax Credit Score Matters

A lender checking your Equifax score directly shapes the offer you get. A score in the ‘Good to Excellent’ range typically means faster approval, access to higher loan amounts or credit limits, and interest rates meaningfully below what a Fair or Poor score would attract.

On a large loan like a home loan, even a ‘one percentage point difference’ in rate adds up to lakhs over the tenure, so the score is a real input into what the loan ends up costing.

How to Check Your Equifax Credit Score for Free

RBI requires every credit bureau, including Equifax, to give you one free full credit report each year.

A free credit score check Equifax is available directly through the bureau’s own website, and through several bank and NBFC partner portals that pull the same underlying score. The first check is typically free. After that, some portals charge a small fee for repeat or updated reports.

 Information Required to Check Your Score

Keep these details handy before you start, since Equifax uses them to match you to the right credit file:

  • Full name and date of birth, exactly as they appear on your PAN card
  • PAN card number to verify your identity
  • Aadhaar number, which Equifax also asks for during registration
  • Mobile number and email address, verified by OTP
  • Current address with PIN code

 Step-by-Step Process to Check Equifax Score Online

If you have been searching, “check my credit score Equifax,” here’s how to get yours:

  1. Go to the Equifax portal or a partner lender’s credit score check page
  2. Enter your PAN, full name, date of birth and contact details
  3. Verify your mobile number or email with the OTP sent to you
  4. Submit the form and wait a minute or two while the report is generated
  5. View your score and download the full credit report for your records

Equifax vs Other Credit Bureaus (CIBIL, Experian, CRIF)

All four RBI-licensed bureaus, Equifax, CIBIL, Experian and CRIF High Mark, draw from largely the same pool of data. Banks and NBFCs report your repayment behaviour to all of them. What differs is the algorithm each bureau uses to weigh that data, which is why your Equifax score and your CIBIL score can land a few points apart even though nothing about your actual borrowing changed.

None of the four is the “official” one that overrides the others. A lender might pull just one bureau’s report or cross-check more than one, depending on their internal policy. Keeping all your repayments on track is the only lever that reliably moves every bureau’s score in the same direction.

Also read: CIBIL vs Experian vs Equifax credit score

How to Improve Your Equifax Credit Score

Steady habits improve your Equifax score more than quick fixes:

  • Pay in full and on time: Set up auto debit mandates for EMIs and credit card bills to avoid missed payments
  • Keep utilisation low: On a ₹1 lakh total limit, try to keep your outstanding balance below ₹30,000
  • Balance your credit mix: Combine secured loans, like a home loan, with unsecured credit, like a credit card
  • Limit enquiries: Each application triggers a hard enquiry and has an implication on application, so avoid applying to several lenders within a few weeks
  • Review your report: Check your report yearly and dispute incorrect entries on the website of Equifax

Also read: How to increase CIBIL score from 600 to 750

Common Reasons for a Low Equifax Credit Score

Most low scores trace back to a few repeat patterns:

  • Missed or delayed payments: Late EMI or credit card payments are recorded as days past due (DPD) and tend to impact scored adversely
  • High utilisation: Carrying ₹90,000 on a ₹1 lakh limit month after month signals over-reliance on credit and adversely impacts credit score
  • Loan settlements: Paying less than the full amount owed gets marked as “settled”, which lenders read as a partial default
  • Too many enquiries: Applying to several lenders in a short span adds multiple hard enquiries which has an adverse impact
  • Unflagged errors: A loan that isn’t yours or a closed account shown as active can lower your score until disputed

Also read: Days past due in CIBIL report

How Often Should You Check Your Equifax Credit Score?

Checking your own score is a soft enquiry, and soft enquiries don’t affect your credit score at all, so there is no downside to checking often.

A quarterly check is a reasonable habit for most people, enough to catch errors or fraud early, without becoming a fixation. If you’re actively planning to apply for a loan in the next few months, it’s worth checking a little closer to that date too, so there is time to fix anything that might hold up approval.

 Conclusion

Your Equifax credit score is one of several numbers lenders look at, but it’s a real factor in whether you get approved and at what rate. The mechanics behind it are fairly simple even if the exact algorithm is not public. Pay on time, keep utilisation low, and don’t apply for credit you don’t need. Check your score for free every few months, keep an eye on your report for errors, and the score number tends to take care of itself.

Ready to see where you stand? Check your credit score for free with Tata Capital in just a couple of minutes.#

FAQs

What is a good Equifax credit score?

A score of 670 or above is generally considered good, with 740 and upward counted as Very Good to Excellent. Most lenders offer their best rates and fastest approvals to applicants in this upper range.

How is Equifax credit score different from CIBIL score?

Both the scores run on a 300-900 scale and draw from similar repayment data reported by banks and NBFCs, but each bureau uses its own scoring algorithm and weightage, so the two numbers can differ slightly for the same person at the same time.

Is checking my Equifax credit score free?

Yes, the first check is typically free through Equifax's own portal or a partner lender's site. Some platforms charge a small fee for repeat or continuously updated reports afterward.

Does checking my Equifax score affect my credit rating?

No. Checking your own score counts as a soft enquiry, which has no impact on your credit score. Only hard enquiries, triggered when a lender checks your report as part of a loan or card application, can affect it.

What documents are needed to check Equifax credit score?

You will typically need your PAN card, full name, date of birth, and a mobile number or email address for OTP verification. No physical documents need to be uploaded for the basic online check.

How often is the Equifax credit score updated?

Equifax receives updated repayment data from banks and NBFCs on a regular basis, generally weekly, so your score can shift as new repayment information comes in.

What is the highest possible Equifax credit score?

The scale tops out at 900. Scores of 800 and above fall in the Excellent band, where approvals are easiest and interest rates are typically the most competitive.