Get the Tata Capital App to apply for Loans & manage your account. Download Now

Blogs

SUPPORT

Tata Capital > Blog > Wealth Services > What Are Hybrid Mutual Funds? Meaning and Types 

Wealth Services

What Are Hybrid Mutual Funds? Meaning and Types 

What Are Hybrid Mutual Funds? Meaning and Types 

Summary: A hybrid mutual fund invests in a mix of asset classes, typically equity and debt, and sometimes gold or REITs, inside a single fund. This blog covers what hybrid mutual funds mean, how the fund actually balances growth against stability and the seven SEBI-defined categories. You will also find how taxation depends on the fund’s equity share rather than its “hybrid” label, the benefits and risks involved and how to match a category to your own risk appetite and horizon.

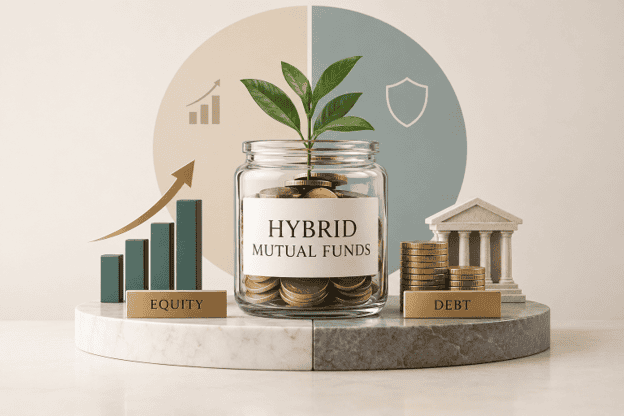
Hybrid mutual funds invest in a mix of asset classes (typically equity and debt) and sometimes gold or REITs, all within a single fund, so the fund manager handles the asset allocation on your behalf rather than leaving you to split your money across separate schemes.

Understanding hybrid funds starts with that basic trade where you give up some control over the exact mix in exchange for one professionally managed portfolio. This blog covers the meaning of hybrid funds in plain terms, the seven categories SEBI has defined for this space, how each is actually taxed, the risks alongside the benefits and how to match a category to your own situation.

Note: Hybrid funds carry moderate risk (not no risk) and their returns remain market-linked throughout.

Hybrid Mutual Fund Meaning

A hybrid mutual fund pools money and invests across equity and debt, and sometimes gold or REITs, in one portfolio. It aims to balance the growth potential of equity with the relative stability of debt. The fund manager sets and adjusts this mix.

That is what hybrid mutual fund structure is at its core, and this hybrid fund’s meaning stays consistent across every variant you will encounter. Only the specific proportions and the manager’s flexibility change from one category to the next.

How Do Hybrid Funds Work?

A hybrid fund allocates your money across equity, which drives growth; and debt, which provides stability and income in a ratio set by its category. Some categories use a static band (a fixed range the fund must stay within) while others are dynamic, letting the manager shift the mix as market valuations change. The equity portion is what largely drives the fund’s returns over time, while the debt portion is designed to cushion the impact when equity markets fall. Because both pieces move independently, the fund’s overall NAV reflects the combined behaviour of its equity and debt holdings rather than either one alone.

The practical appeal of this fund is simplicity. The manager handles the ongoing rebalancing between equity and debt, so you are not left tracking and adjusting two separate investments yourself.

However, this kind of convenience does not remove market risk. Hybrid fund returns remain linked to how the underlying equity and debt markets perform and they are not guaranteed.

Types of Hybrid Mutual Funds (SEBI Categories)

SEBI defines seven distinct categories under the hybrid label, each with its own equity-debt band and risk profile:

CategoryEquity-Debt MixRiskBest Suited For
Conservative10%-25% equityLowerCautious investors, near-term goals
Balanced40%-60% equityModerateInvestors wanting a middle ground (cannot use arbitrage)
Aggressive65%-80% equityHigher, more volatileLong-term growth with some debt cushioning
Balanced Advantage / Dynamic Asset AllocationRoughly 30%-80% equity, shifted by the manager based on valuationsVaries with the manager’s callsInvestors who want the fund to manage market timing for them
Multi-Asset AllocationAt least 10% each across three or more asset classes, including gold or REITsModerate to high, depending on the mixInvestors seeking diversification beyond equity and debt
Equity SavingsRoughly 15%-40% net equity, with the rest in debt and arbitrageLower to moderateInvestors wanting steadier, more tax-efficient exposure
ArbitrageEquity and equivalent derivative positions, largely market-neutralLowShort-term, tax-efficient parking of money

A Balanced Advantage or Dynamic Asset Allocation fund is worth a specific mention. By letting the manager shift the equity-debt mix as valuations change, it is designed to solve the common behavioural problem of buying more when markets are expensive and panic-selling when they fall.

Arbitrage funds work differently from the rest of this list.  They generate low-risk returns from price differences between the cash and derivatives markets. Categories toward the higher end of the equity range, i.e., aggressive, balanced advantage, equity savings and arbitrage generally qualify for equity taxation. 

How Hybrid Funds Are Taxed

Taxation on a hybrid fund depends on its actual equity allocation and not on the fact that it carries a “hybrid” label. This is the detail that trips up a lot of investors.

Funds holding 65% or more in equity are taxed as equity funds:

  • Long-term capital gains for units held over 12 months, are taxed at 12.5% above the ₹1.25 lakh annual exemption.
  • Short-term gains, for units held 12 months or less, are taxed at 20%.

Funds holding less than 35% in equity get debt fund taxation instead, meaning gains on units bought on or after 1 April 2023 are taxed at your income slab rate regardless of holding period, with no indexation available.

Funds that fall in between, holding 35% to under 65% in equity, follow a separate rule introduced by the Finance Act, 2024. Here:

  • Long-term gains for units held over 24 months are taxed at 12.5%.
  • Gains on units held 24 months or less are taxed at your income slab rate.

In practice, this means an aggressive hybrid fund, a balanced advantage fund, an arbitrage fund or an equity savings fund with sufficient net equity exposure usually enjoys equity taxation. This is often an underappreciated draw of this category.

Tax rules get revised through the Union Budget. Verify your specific fund’s classification and the current rates with a qualified chartered accountant.

What Changed in 2026: New SEBI Classification Rules

SEBI issued a revised mutual fund categorisation circular on 26 February 2026, effective 1 April 2026, that refined several hybrid fund rules.

  • Arbitrage funds now face tightened debt-exposure limits, restricted to government securities maturing within one year and repos on government bonds. They can no longer invest in InvITs.
  • Equity Savings funds must now disclose a minimum net or unhedged, equity exposure of 15% in their scheme documents, alongside their maximum arbitrage and hedged exposure. This was not previously mandated.
  • Separately, most hybrid categories, with the specific exception of arbitrage funds are now permitted to invest a residual portion of their portfolio in InvITs, exchange-traded commodity derivatives and gold or silver ETFs, thereby adding a further layer of diversification within a single scheme.

Benefits and Risks of Hybrid Funds

The benefits here are real, but they come with trade-offs worth stating plainly alongside them.

Benefits

On the benefit side, a hybrid fund gives you built-in diversification and asset allocation within one scheme, rather than requiring you to manage separate equity and debt investments yourself.

The debt component typically cushions drawdowns meaningfully during equity downturns, often reducing the fall by somewhere in the range of 30% to 50% compared with a pure equity fund, depending on the category’s equity share.

Where a fund qualifies for equity taxation (as several hybrid categories do), that adds a further practical advantage.

And because the manager handles rebalancing, this category tends to suit beginners or investors targeting a specific goal without wanting to actively manage two separate portfolios.

Risks

On the risk side, a hybrid fund is still market-linked and can lose value. This is not a capital-protected product. The equity portion carries the same market risk any equity holding does, while the debt portion carries its own interest-rate and credit risk.

Risk also varies considerably within the category itself. An aggressive hybrid fund is meaningfully riskier than a conservative one. So the label “hybrid” alone tells you little without knowing the specific equity band.

In a strong sustained bull market, a hybrid fund’s returns will generally lag a pure equity fund, since the debt portion caps some of the upside in exchange for the downside cushioning. Matching the specific category to your own risk appetite and horizon rather than assuming all hybrid funds behave similarly, is what determines whether this trade-off actually works in your favour.

How to Choose the Right Hybrid Fund

Matching a category to your situation is more useful than searching for a single “best” hybrid fund, since the right choice depends entirely on your own risk appetite and time horizon.

  • If you are cautious or investing for a near-term goal, a conservative hybrid fund’s lower equity band fits that profile.
  • If you would rather the fund manager handle market timing than do it yourself, a balanced advantage or dynamic asset allocation fund is built for exactly that.
  • If you want long-term growth with some downside cushioning, an aggressive hybrid fund offers a higher equity share while still holding a debt buffer.
  • If diversification beyond equity and debt appeals to you, a multi-asset fund adds gold or other asset classes into the mix.
  • If tax-efficient or relatively low-risk parking of money is your priority, an arbitrage or equity savings fund is generally the more fitting choice.

Beyond matching the category itself, it is worth checking the expense ratio as well, since direct plans typically cost less than regular plans. Look at a fund’s long-term consistency against its benchmark rather than a single one-year chart.

You can also consider speaking with a qualified financial adviser if you remain unsure which category fits your goals. You can explore hybrid funds available through Tata Capital Moneyfy as part of your own research. Tata Capital is an AMFI-registered distributor and does not recommend specific schemes.

Conclusion

Hybrid mutual funds combine equity and debt and sometimes further asset classes, within one professionally managed vehicle. SEBI’s seven categories run from conservative through to aggressive, multi-asset, equity savings and arbitrage.

Taxation hinges on the fund’s actual equity share rather than its label, with 65% or more in equity qualifying for equity taxation, i.e., a feature several categories in this space enjoy. Hybrid funds offer real diversification and generally lower volatility than pure equity, but they remain moderate risk. Hence, choosing by your own risk profile and horizon matters more than chasing a specific category’s recent returns. You can also explore hybrid funds on Tata Capital Moneyfly as a next step.

Disclaimer: Tata Capital (Moneyfy) is an AMFI-registered mutual fund distributor. Mutual fund investments are subject to market risk. Please read all scheme related documents carefully. Consult a qualified chartered accountant or financial adviser regarding your specific tax position, before investing.

FAQs

What is a hybrid mutual fund?

A hybrid mutual fund invests across more than one asset class, typically equity and debt, within a single scheme, aiming to balance equity's growth potential against debt's relative stability. This is the practical hybrid fund meaning, i.e., one fund, one manager and a blended risk profile rather than pure equity or pure debt exposure.

What are the types of hybrid funds?

SEBI defines seven categories: Conservative (10%-25% equity), Balanced (40%-60%), Aggressive (65%-80%), Balanced Advantage or Dynamic Asset Allocation (manager-adjusted), Multi-Asset Allocation (three or more asset classes), Equity Savings (roughly 15%-40% net equity) and Arbitrage (largely market-neutral). Each carries a distinct risk level and suits a different kind of investor.

How are hybrid mutual funds taxed?

Taxation depends on equity allocation: funds with 65% or more in equity get equity taxation, funds with less than 35% get debt taxation at your slab rate and funds in between (holding 35% to under 65%) follow a separate rule taxing long-term gains (over 24 months) at 12.5% and shorter-term gains at your slab rate.

Are hybrid funds safe?

Not in the sense of being risk-free. Hybrid funds are moderate risk, i.e., they carry less volatility than a pure equity fund. However, they still move with the market and can lose value, since both the equity and debt portions carry their own respective risks. The specific risk level varies significantly by category.

What is a balanced advantage fund?

A balanced advantage fund, also called a dynamic asset allocation fund, is a hybrid mutual fund where the manager actively shifts the equity-debt mix (roughly between 30% and 80% equity) based on market valuations. The aim is to automatically increase equity exposure when markets look attractively priced and reduce it when they look expensive, without you having to time it yourself.

What is an arbitrage fund?

An arbitrage fund is a type of hybrid fund that generates low-risk returns by simultaneously buying a stock in the cash market and selling an equivalent position in the derivatives market, profiting from the small price gap between the two rather than from market direction. If you are asking what is an arbitrage fund doing differently from other hybrid categories, this market-neutral strategy is the answer. And because it holds a high equity allocation, it typically qualifies for equity taxation despite its low market risk.

Are hybrid funds good for beginners?

Yes, generally. Hybrid funds can suit beginners well, since the manager handles the asset allocation and rebalancing between equity and debt on your behalf. This removes some of the complexity of managing separate investments. That said, the right category still depends on your own risk appetite and goal, so a conservative or balanced option often makes more sense for a first-time investor than an aggressive one.