Get the Tata Capital App to apply for Loans & manage your account. Download Now

Blogs

SUPPORT

Tata Capital > Blog > NPS Tier 1 vs Tier 2: Differences, Returns & Tax Treatment

Wealth Services

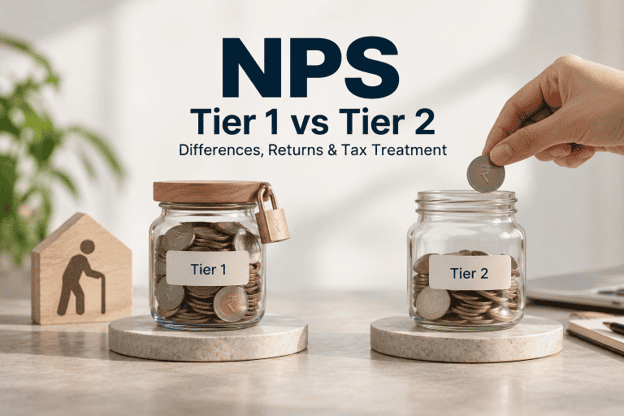
NPS Tier 1 vs Tier 2: Differences, Returns & Tax Treatment

NPS Tier 1 vs Tier 2: Differences, Returns & Tax Treatment

Summary: NPS has two account types, Tier I and Tier II, under the same PRAN but are different in terms of withdrawal rules, liquidity and tax treatment. Tier I is the primary pension account with limited withdrawals and tax benefits, while Tier II is an optional investment account with flexible withdrawals and usually no tax benefits. The returns are linked to the market and depend on the chosen investment profile and pension fund.

The National Pension System (NPS) provides two account types, Tier I and Tier II, under a single Permanent Retirement Account Number (PRAN). Both accounts can provide exposure to the same broad asset classes and pension fund managers, but their rules differ significantly. Tier I is the default pension account with restricted withdrawals and tax benefits, while Tier II is an optional investment account with greater withdrawal flexibility and generally no tax benefits. This guide explains the key differences between national pension scheme tier 1 and nps tier 2, including contributions, withdrawals, returns and tax treatment.

What Is NPS Tier 1?

NPS Tier I is the primary pension account under NPS and the default account for subscribers. It is a retirement-focused account with regulated withdrawal and exit conditions and is eligible for applicable tax benefits under the Income Tax Act. Under the All Citizen Model, Indian citizens, NRIs and OCIs aged 18 to 85 years can subscribe, subject to KYC and other eligibility conditions.

The minimum contribution to open a Tier I account is ₹500, while the minimum contribution required in a financial year is ₹1,000. There is no upper limit on the amount a subscriber can contribute.

Tier I does not simply have a blanket lock-in until age 60 under the current rules. For the All Citizen Model, the revised exit framework provides for normal exit after 15 years of subscription or on attaining 60 years of age, whichever is earlier, subject to the applicable rules. Partial withdrawals are also permitted subject to specified conditions.

Also Read – Types of mutual funds in India

What Is NPS Tier 2?

NPS Tier II is an optional investment account that can be opened only by a subscriber who has an active Tier I account. It operates under the same PRAN but provides significantly greater withdrawal flexibility than Tier I. Subscribers can withdraw their accumulated Tier II wealth, fully or partly, at any time.

The minimum amount to open a Tier II account is ₹1,000 and the minimum subsequent contribution is ₹250. Unlike Tier I, there is no prescribed annual contribution requirement for keeping a Tier II account active.

Subscribers can also choose a different pension fund and investment option for Tier II from those selected for Tier I. Tier II therefore operates as an optional, market-linked investment account rather than the primary pension account.

Read More – Wealth creation plan

Key Differences Between Tier 1 and Tier 2

The main difference between nps tier 2 and Tier I is the purpose and level of withdrawal flexibility attached to each account.

FeatureNPS Tier INPS Tier II
PurposePrimary retirement/pension accountOptional investment account
EligibilityAvailable to eligible NPS subscribersAvailable only with an active Tier I account
Minimum opening contribution₹500₹1,000
Minimum subsequent contribution₹500₹250
Minimum annual contribution₹1,000No prescribed annual minimum
WithdrawalsRestricted and subject to NPS withdrawal/exit rulesFull or partial withdrawal permitted at any time
Investment choicesPension fund and investment pattern can be selectedDifferent pension fund and investment option can be selected from Tier I
Tax treatmentEligible for applicable NPS tax benefitsGenerally no tax deduction on contributions or special tax treatment on gains
Tier II Tax Saver SchemeNot applicableAvailable to eligible Central Government employees, subject to separate rules

Tier I is structured around retirement savings and regulated withdrawals, whereas Tier II provides greater liquidity. Tier II withdrawals do not require the purchase of an annuity.

The withdrawal rules for Tier I have also changed over time. Current PFRDA rules should be checked for the applicable subscriber category because exit and partial-withdrawal conditions can differ by model and employment sector.

Also Read – SIP rules & 7-5-3-1

NPS Tier 2 Returns: What to Expect

NPS Tier 2 returns are market-linked and are not fixed or guaranteed. The account can invest across permitted asset classes such as equity, corporate debt and government securities, depending on the subscriber’s selected investment pattern. The return therefore depends on the underlying assets, allocation and performance of the selected pension fund.

Tier I and Tier II can use the same broad asset classes and pension fund managers, but they do not necessarily have to follow the same investment choice. A subscriber can select a different pension fund and investment option for Tier II.

Therefore, nps tier 2 returns should not be assumed to match Tier I returns. Historical NAV or scheme performance can differ across pension funds, schemes and investment patterns, and past performance does not guarantee future returns.

Note: No specific historical return percentage is stated here because NPS Tier 2 returns change with market performance and vary across schemes and pension funds.

Read More – Retirement Planning in India

Tax Treatment: Tier 1 vs Tier 2

Tier I and Tier II receive different tax treatment. Eligible Tier I contributions can qualify for deductions under applicable provisions of Section 80CCD, including Section 80CCD(1), the additional ₹50,000 deduction under Section 80CCD(1B) under the old tax regime, and eligible employer contributions under Section 80CCD(2).

Tier II contributions generally do not qualify for the same NPS contribution deductions, and gains do not receive a special NPS tax treatment for most subscribers. The Income Tax Department specifically provides a deduction under Section 80C for contributions to a Tier II account by a Central Government employee, subject to conditions including a three-year lock-in.

This Tier II Tax Saver Scheme is distinct from the regular Tier II account. It is available only to eligible Central Government NPS subscribers and carries a three-year lock-in for the tax benefit.

For regular Tier II withdrawals, gains do not receive the tax treatment applicable to the tax-exempt portions of eligible Tier I exits. PFRDA’s tax guidance states that Tier II does not receive tax benefits on contributions or special tax treatment for gains.

Tier I exit taxation is different. Under the applicable rules, the permitted lump-sum portion at exit can receive tax-exempt treatment, while the annuity purchase amount is exempt at the time of purchase and the subsequent annuity income is taxable according to the applicable provisions.

Also Read – NPS vs PPF vs Mutual Funds

Which Should You Choose: Tier 1, Tier 2, or Both?

The choice between national pension scheme tier 1 and nps tier 2 depends on the account’s intended purpose, liquidity requirement and applicable tax treatment.

Tier I is structured as the primary pension account and has regulated withdrawal and exit conditions. Tier II provides greater access to the accumulated balance and can be used as an additional market-linked investment account.

A subscriber who has an active Tier I account can hold both accounts and select different pension funds or investment options for each. Whether one or both accounts are relevant depends on factors such as the intended investment horizon, need for liquidity, applicable tax provisions and the subscriber’s overall financial circumstances.

Tier II should not be treated as equivalent to a bank savings account or a guaranteed-return deposit because its value is linked to market performance.

Also Read – Unified Pension Scheme (UPS)

Conclusion

NPS Tier I and Tier II are two different account types within the same NPS framework. Tier I is the primary pension account with regulated withdrawals and applicable tax benefits, while Tier II is an optional investment account with greater withdrawal flexibility and generally no tax benefit.

Their returns are market-linked and can vary based on the selected investment pattern, asset allocation and pension fund. Current contribution minimums, withdrawal conditions and tax provisions should be checked against the latest PFRDA, NPS Trust and Income Tax Department rules before making account-level decisions.

For general information on retirement and wealth planning, you can explore more on Tata Capital Wealth Services.

Disclaimer: This article is for general educational purposes only and does not constitute tax, financial or investment advice. NPS contribution requirements, withdrawal rules, tax provisions and investment-related regulations may change. Readers should verify the provisions applicable to their NPS model and tax year with the latest PFRDA, NPS Trust and Income Tax Department information or consult a qualified tax or financial professional.

FAQs

What is the difference between NPS Tier 1 and Tier 2?

NPS Tier I is the primary pension account with regulated withdrawals and applicable tax benefits. NPS Tier II is an optional account available to subscribers with an active Tier I account and permits withdrawals at any time. Both are market-linked, but their contribution, withdrawal and tax rules differ.

Can I open a Tier 2 NPS account without a Tier 1 account?

No. An active Tier I account is required to open an NPS Tier II account. Tier II is an optional investment account linked to the subscriber's existing PRAN. Once opened, Tier II allows full or partial withdrawals at any time, subject to applicable account and transaction requirements.

What returns can I expect from NPS Tier 2?

NPS Tier 2 returns are market-linked and are not fixed or guaranteed. They depend on the selected pension fund, investment pattern and underlying asset allocation. Since subscribers can choose different investment options for Tier I and Tier II, returns in the two accounts may differ.

Does NPS Tier 2 offer any tax benefit?

Regular NPS Tier II contributions generally do not qualify for tax deductions. However, eligible Central Government employees can claim a deduction for contributions to the Tier II Tax Saver Scheme under Section 80C, subject to conditions including a three-year lock-in. The regular Tier II account does not receive this tax treatment.

Is there a lock-in period for NPS Tier 2?

A regular NPS Tier II account does not have a lock-in and permits withdrawals at any time. The exception is the Tier II Tax Saver Scheme available to eligible Central Government employees, where contributions qualifying for the Section 80C deduction are subject to a three-year lock-in.

Can I withdraw the entire Tier 2 balance at once?

Yes. A subscriber can withdraw the entire accumulated Tier II balance or part of it at any time. There is no NPS-prescribed withdrawal limit for a regular Tier II account, provided sufficient balance remains to cover applicable charges and the requested withdrawal.

Should I invest in both Tier 1 and Tier 2?

There is no universal answer. Tier I is structured for retirement savings with regulated withdrawals and applicable tax benefits, while Tier II provides greater liquidity through unrestricted withdrawals. A subscriber can hold both and choose different investment options for each, depending on their objectives, liquidity requirements and tax position.