Tata Capital > Blog > Loan for Business > Dairy farm loans in India: Eligibility, benefits & online application

 30 October 2026
 10 mins read
 2447

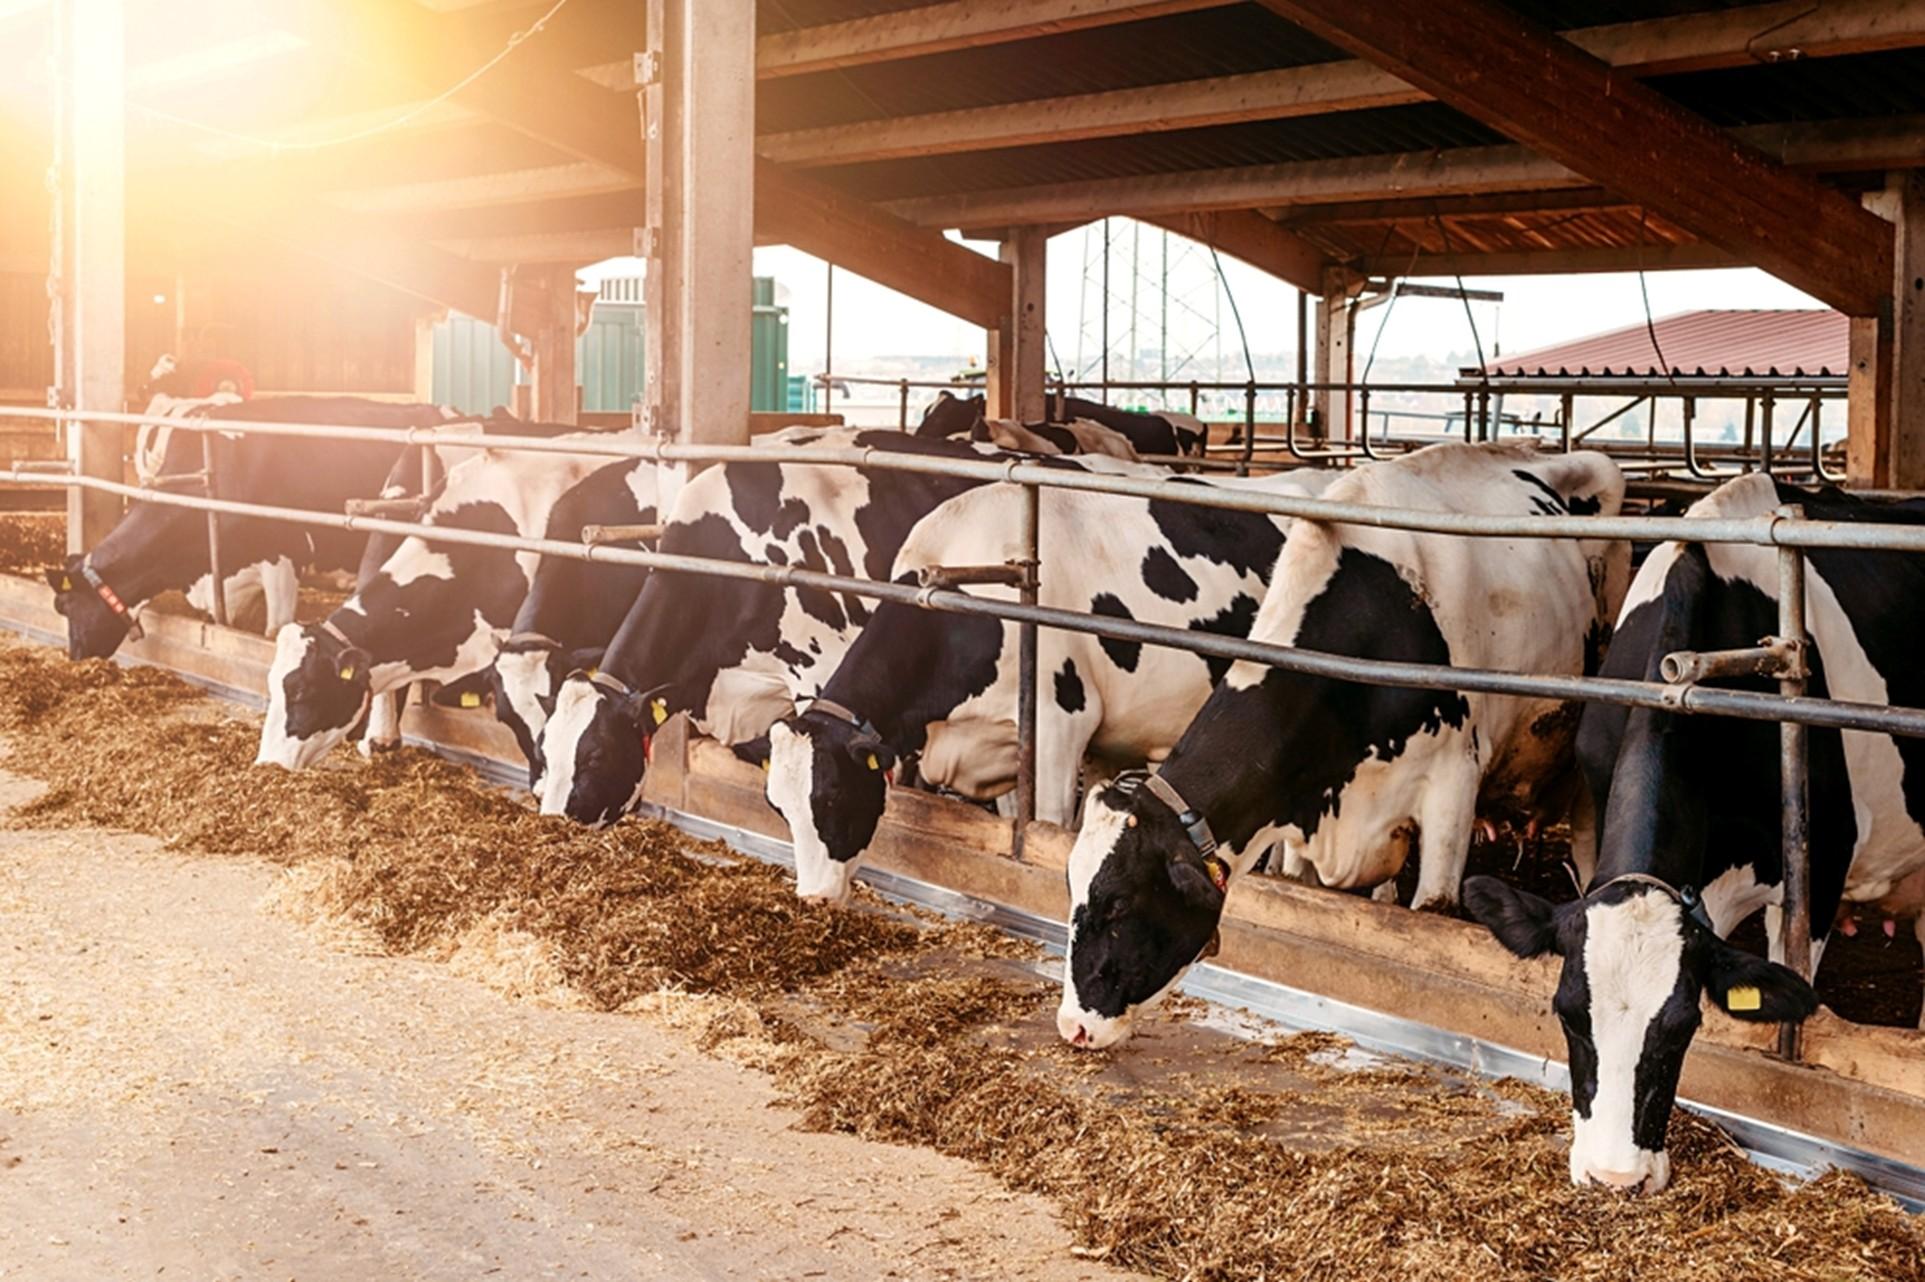
Dairy farming has been a popular source of income in rural India. It strongly supports many families, communities, and economies. In fact, it is one of the leading contributors to the agricultural sector, promoting economic growth and providing livelihood for millions of farmers. However, if you want to step into dairy farming, you need a significant investment. Fortunately, most financial institutions in India offer dairy farm loans to help you start or expand dairy farm operations.
This article helps you understand the important details of a dairy loan, its interest rates and charges, and the application process.
A dairy farm loan is an agricultural loan offered by banks or NBFCs to people who run or want to run a dairy farm. It provides money to help you buy cows or buffalo, build sheds, and purchase feed. You can also use the funds to install milking machines and manage daily expenses. The purpose of the loan is to help farmers increase milk production and earn a steady income. It aims to support rural livelihoods and strengthen the dairy supply chain.
Farmers and agribusiness owners can use dairy farm loans to expand herds, improve equipment, set up cold storage, or handle working capital needs. The repayment is usually done in monthly or seasonal installments from milk sales.
Here’s a quick overview of the essential features and benefits of dairy farm loans:
With a dairy farm loan, you can get a high loan amount based on the farm size, assets, and repayment ability. Larger funding helps farmers buy more cattle, build larger sheds, install modern milking machines, and improve storage. Higher limits also allow farmers to expand production, serve more buyers, and grow income. This support makes it easier to scale dairy operations and run a profitable farm.
Dairy farm loans are flexible, allowing farmers to choose a plan based on their income cycle. Some loans work like flexi loans or overdrafts. Farmers can withdraw money as needed and pay interest only on the amount used. You can adjust the repayment terms according to milk sales.
Flexible loan options make it easier for you to handle emergencies. You can also manage cash flow better. As your financial burden reduces, you can focus on running and expanding your dairy farm business.
Many lenders now provide faster approval for dairy farm loans. With the dairy loan apply online option, farmers can complete the application from home. The loan can also be tracked without visiting the branch. Basic checks and e-KYC speed up verification. Some loans get approved in a few days instead of weeks. Such quick processing helps farmers make timely purchases of cattle, feed, or equipment. It ensures there are no delays in farm operations.
Some dairy farm loans are available without collateral, especially under government or small-business schemes. These unsecured loans are given based on credit history, farm income, and a clear business plan. The loan amounts may be smaller, with the interest rate slightly higher. Farmers must meet eligibility rules to qualify. Installments must also be paid on time to avoid penalties. Collateral-free options help new or small farmers easily start and grow dairy operations.
Dairy farm loans offer convenient repayment tenures to match farm income. Farmers can choose monthly or quarterly EMIs based on milk sales. The tenure may range from 1 to 7 years, depending on the loan size. Flexible schedules make repayments easier during low-income periods, helping farmers manage cash flow while running and gradually expanding their dairy business.
The eligibility conditions for a dairy farm loan are simple and open to many farmers and agribusiness owners. Lenders check whether the applicant can run a dairy unit and repay the loan on time. Both new and existing dairy farms can apply if they meet basic requirements.
You qualify for a dairy loan if you fulfill the following criteria:
Many lenders prefer applicants with some dairy or farming experience before giving a loan. Usually, 6 months to 2 years of business activity is sufficient. However, it depends on the specific lender’s conditions. Farming experience shows that you understand animal care, milk production, and daily operations. You may need to provide proof such as milk sale records, bank statements, supplier bills, or cooperative membership.
If you’re a new farmer, you can apply with a clear business plan. You may need to prove that you have basic training in dairy farming and management.
Dairy farm loan applicants must meet the basic age rules set by lenders. The minimum age is usually 18 or 21 years. You must be an adult, permitted to sign legal loan documents. The maximum age at loan maturity is often 60 to 65 years. Lenders set such an age limit to ensure that the borrower is fit to manage the farm and repay the loan on time.
Younger and middle-aged farmers have better chances of approval. Older applicants may still qualify if they apply with a co-applicant or family member involved in the dairy business.
Lenders check an applicant’s CIBIL score to verify how they have repaid past loans. For a dairy farm loan, a score of about 650 or above is usually preferred. A higher score improves approval chances and may help you get lower interest rates or better terms. If the score is low, the loan may still be possible, but with stricter conditions, a guarantor, or a higher interest rate.
It is possible to improve your credit score. You must remember to pay EMIs on time and clear all dues. You must also check your credit report periodically and get any errors you spot rectified immediately.
To apply for a dairy farm loan, you must be an Indian citizen and resident. Most banks and finance companies require proof that you live and work in India. The common documents include an Aadhaar card, voter ID, passport, or ration card for identity and address proof. The dairy farm should also operate within India.
Non-resident Indians may face limits or need special conditions. If you have clear proof of residency and citizenship, it helps lenders verify your identity and process the loan smoothly and quickly.
The documents you require to proceed with the dairy farm loan online application are:
There are various advantages of taking a dairy farm loan. These include:
Interest rates on dairy farm loans vary by bank, lender, and government schemes. They range from about 8% to 15% per year, depending on credit score, loan amount, and repayment history. Some government-supported loans offer lower subsidized rates for farmers.
Lenders may also charge a processing fee, often around 0.5% to 2% of the loan amount. Other possible charges include documentation fees, late payment penalties, and pre-payment or foreclosure fees if the loan is closed early. You must compare offers, read terms carefully, and understand all costs before applying for a dairy loan.
The step-by-step process to apply for a dairy farm loan online is as follows:
The offline application process requires you to visit a nearby branch. You need to submit forms and documents in person and complete verification with the loan officer for processing and approval.
If you want to apply for a dairy loan online, here’s what you need to do:
Yes, new farmers can apply for a dairy farm loan. Lenders may ask for a simple business plan, training proof, or a guarantor. Government schemes and small-ticket loans often support beginners starting or planning to start dairy operations.
No, poultry and fisheries loans are usually separate from dairy farm loans. However, many banks offer combined agriculture or livestock loans that cover dairy, poultry, and fisheries under one broader farming or agribusiness financing scheme.
The maximum tenure for a dairy farm loan usually ranges from 1 to 7 years. Some large or government-backed loans may go up to 10 years. The tenure depends on loan size, assets purchased, and repayment ability.
Yes, many lenders allow pre-payment or foreclosure of a dairy farm loan. Some may charge a small fee for early closure. Paying the loan early reduces interest costs and helps clear debt faster.
The best loan for dairy farming depends on needs and eligibility. Government-backed agriculture loans, Kisan Credit Card loans, and bank dairy farm schemes are popular. Make sure you compare interest rates, tenure, subsidy options, and flexibility before choosing.
The State Bank of India offers dairy farm loans based on project cost and repayment ability. Loan amounts can range from small amounts for a few cattle to several lakhs for larger farms. The exact limits depend on the proposal.
An MSME loan for dairy farms is given to small dairy businesses registered as micro or small enterprises. It helps with working capital, equipment, and expansion. These loans may offer easier approval, subsidies, and flexible repayment terms.


 Previous Post