Tata Capital > Blog > Credit Score > What are credit bureaus and how do they work in India?

 12 June 2026
 8 mins read
 3348

Summary
A credit bureau refers to a company that gathers and maintains financial data about an individual’s borrowing and repayment history. It is also known as a credit reporting agency. The data stored with a credit bureau is used to prepare your credit report and estimate your credit score. The credit score is a three-digit number used by lenders to assess your creditworthiness before sanctioning a loan or a credit card. India has four primary credit bureaus, including Experian, Equifax, TransUnion CIBIL, and CRIF High Mark. These are regulated by the Reserve Bank of India (RBI).
A credit bureau collects financial data from lenders, credit card companies, and financial institutions to compile your credit report and calculate your credit score.
In today’s world, getting a loan during a financial emergency has become a fairly simple process. But have you ever wondered what happens behind the scenes when lenders decide to approve your loan?
It all comes down to your credit history. This crucial record reflects your past borrowing behavior, giving lenders an idea of how well you manage debt and whether you’re likely to repay on time. At the core of this system are credit bureaus. These organizations carefully maintain credit histories for a wide range of borrowers.
Their primary role is to support responsible lending by helping both borrowers and lenders make informed decisions. To know more about the credit bureau’s meaning, and how they operate, continue reading.
Credit Bureaus, or credit reporting agencies, are databases that collect and store numerous individual financial behavior data. This data includes details about payment history, credit accounts, and outstanding debts.
Non-banking financial companies (NBFCs), banks, credit card companies, and other financial institutions are some of the major clients of credit bureaus. In India, credit bureaus are regulated by the Credit Information Companies (Regulation) Act, 2005, and the Reserve Bank of India (RBI).
Also, read – Experian vs CIBIL
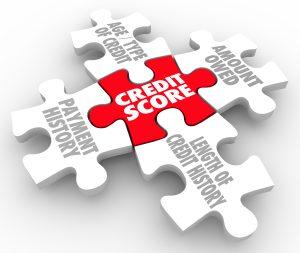
A credit score is a three-digit number that shows how responsible you are when it comes to managing borrowed money. It depends on factors such as repayment history, credit usage, and credit inquiries. The credit score is estimated by an agency known as a credit bureau. For the purpose of this calculation, bureaus obtain the data from banks, financial institutions, and credit card companies. Credit bureaus use this collected information to create a credit report. It helps lenders assess your creditworthiness.
In India, there are four major credit bureaus that collect borrowers’ past financial records. They are:
TransUnion CIBIL is one of the top credit bureaus in India that keeps track of millions of credit reports in its vast database. These reports include detailed records on credit histories, how people pay back loans, and their credit scores. The main purpose of TransUnion CIBIL is to empower lenders to evaluate creditworthiness effectively, enabling them to make smart, informed lending decisions.
Equifax is a major player in the world of credit information, extending its services into India as well. This company meticulously gathers credit data from various sources to create comprehensive reports and scores for businesses and individual borrowers.
Experian is yet another top credit bureau in India that plays an important role in tracking credit information. It gathers credit-related information from various sources, producing insightful credit reports and scores.
CRIF High Mark is also one of the top credit bureaus in India. It focuses on providing solid credit information and risk management solutions so businesses can understand their financial standing and make informed financial decisions. Like the rest of the credit bureau types, the CRIF High Mark also provides detailed credit reports and scores from various sources.
Also, read – CIBIL score vs. credit score
Credit bureaus are pivotal players in the financial landscape, serving as trusted intermediaries between consumers and various lending institutions. It helps in:
Credit bureaus act as financial scouts in gathering credit information from various sources, such as banks, non-banking financial companies (NBFCs), credit card issuers, and other financial institutions. This information includes credit accounts, payment history, defaults, bankruptcies, and credit inquiries, which are then converted into comprehensive credit reports.
Besides collecting credit data, these bureaus help maintain it diligently. They update the database with the latest changes. For instance, the information is meticulously sourced and updated when you open or close an account, make a payment, or experience any defaults or bankruptcies. This is to make sure that the database provides accurate and up-to-date results.
One of the noteworthy services provided by credit bureaus is the creation of credit reports, which serve as a detailed narrative of your credit history. It highlights key details of your credit history, such as credit accounts, payment habits, defaults, bankruptcies, and inquiries. In short, they provide you with a complete picture of your creditworthiness.
Depending on your credit history, the credit bureaus help determine your credit scores. This is a three-digit score that reveals your overall creditworthiness. It is through this score that a lender decides whether to approve your loan application.
Credit bureaus do not keep credit information to themselves. Instead, they share it with lenders and borrowers. Lenders use these credit reports and scores to evaluate the trustworthiness of a loan applicant. On the other hand, borrowers can check out their own reports and scores to better understand their credit health and where they stand financially.
Also, read – What Does Written-Off Mean in CIBIL?
It is important for borrowers to understand what a credit bureau is for the following reasons:
Here’s how you can get your credit report from a credit bureau in India:
If you find an error in the credit report, you must raise a dispute with the credit bureau by following the steps mentioned below:
As the Indian economy keeps growing, credit bureaus are becoming crucial in the financial ecosystem. They help provide solid insights into creditworthiness and reduce the risks associated with lending.
Want to apply for a loan? Then, check out your credit score and report on the Tata Capital website or app to determine your creditworthiness. Just input your personal details (for new users) or the OTP generated via your mobile number (for old users) to generate the credit score and report in seconds!
Most lenders report borrower information to credit bureaus every month. However, the exact reporting frequency may vary slightly between financial institutions.
No. When you check your own credit report, it is considered a soft inquiry. Credit scores are impacted by hard inquiries, which are generally made by lenders and financial institutions.
Yes, a credit bureau can refuse to correct an error on your credit report if the lender confirms that the reported information is accurate. Moreover, if the evidence you have provided is rejected, your request for correction can be rejected.
Negative information, such as missed payments or loan defaults, may remain on your credit report for several years. It depends on bureau policies.
All four RBI-authorized credit bureaus are reliable in India. However, lenders may prefer one bureau over another based on their internal processes and the efficiency of credit bureau services.
Generally, a credit bureau shares your report with lenders or other authorities only when you give consent. This can be while applying for a loan or a credit card.
The scoring models and data updates may vary from one bureau to another. This can lead to score variations. Lenders usually consider the report they access.
No. You do not need to register with all four bureaus. Your credit bureau information is reported by participating lenders automatically.


 Previous Post